Can You Finance a Condo at Sailport in Tampa?

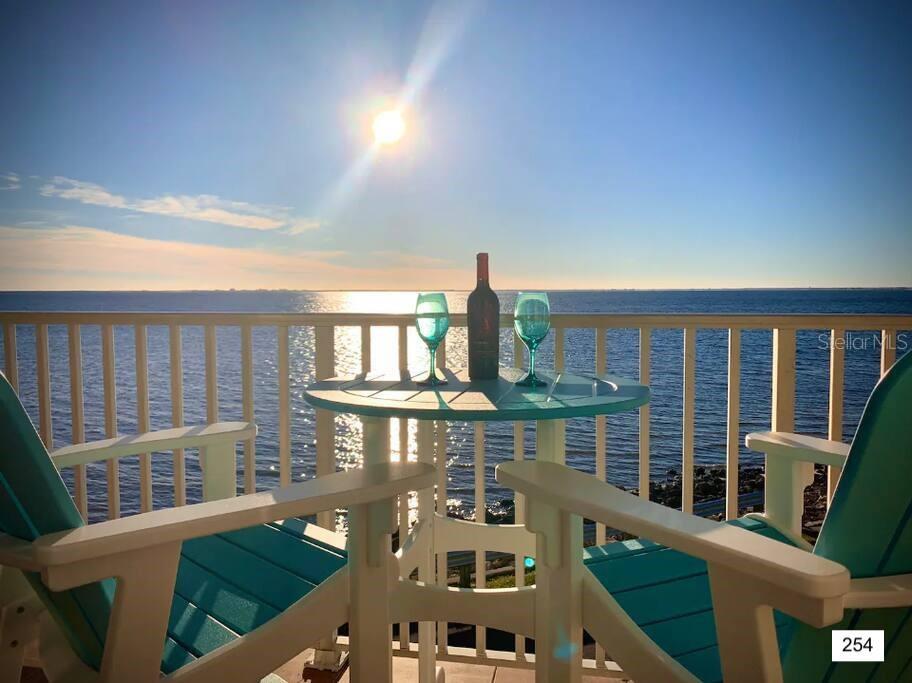
Yes, financing a condo can be possible, but choosing the right lender matters. Sailport is a condo-hotel, also called a condotel, which means financing works differently than it does for a traditional residential condominium.
Mike and I have worked with buyers and sellers in Sailport for six years. One of the biggest lessons we’ve learned: a lender saying “we finance condos” doesn’t necessarily mean they can close a loan here. Yes, we are jaded when a lender comes in and says they can lend on it…..and then they cannot.
Why is Sailport financing different?
Condo-hotels combine individually owned units with hotel-style operations. Each unit is rented out; 2 units are primary homes for owners. It looks like a hotel, but each unit is individually owned. Currently, there is only one condo/hotel in Tampa; they are building one downtown now, and the expected completion is 2028 (I think). The newer condo/hotel is higher-end than Sailport. Personally, I like Sailport because of its affordability, location, and potential cash flow. Jordan and I own a unit there, and I haven’t been in it in over a year. Maintenance is low, and turnover is high.
Condo/Hotels are non-warrantable, meaning they don’t meet the project requirements for standard FSailport annie Mae or Freddie Mac financing. So a bank cannot sell the loan on the secondary market; they have to hold the loan.
Specialized lenders may offer financing, but buyers should expect different underwriting requirements, potentially larger down payments, and possibly higher interest rates. Terms depend on the borrower, property, and loan program.
A buyer’s preapproval is only part of the picture. The lender must also approve the condo project.
What should you ask your lender?
Before committing time and money, ask:
- Does your loan program specifically allow condo-hotels?
- Have you successfully closed loans at Sailport?
- What down payment and documentation will you require?
- When will you review the association documents and building insurance?
A previous closing in the community is helpful experience, but every new loan still requires its own review.
How one document nearly stopped our seller’s closing
In one recent Sailport transaction, final underwriting uncovered what appeared to be a roughly $5 million gap between the building’s insurance coverage and its estimated insurable replacement cost.
One day before closing, our seller’s deal was in jeopardy.
Something didn’t add up, so Mike and I kept asking questions and following up with the association, insurance company, and lender.
After 10 additional days, we uncovered the issue: the October 2024 appraisal supplied to the lender had been rejected by the board. A replacement appraisal was completed that December, but the files being shared hadn’t been updated.
Once the lender received the correct appraisal, the insurance figures aligned, and we received the clear to close.
Experience and persistence matter
Through our work in Sailport, we’ve identified lenders who have successfully financed purchases in the community. We help buyers make those connections and help sellers navigate the questions that can arise along the way.
Thinking about buying or selling at Sailport? Contact Sunny and Mike at Red Sash Group to discuss the property, the process, and where to start with financing.
Everything is figureoutable. And we’re willing to keep asking questions.
Financing availability and terms depend on current lender guidelines, borrower qualifications, and project approval.
Categories
Recent Posts
GET MORE INFORMATION
Broker-Owner